
Markup and gross margin can describe the same sale, but they divide gross profit by different numbers. For one fictional jewelry set that costs $10 and sells for $25, gross profit is $15. The markup is 150% because it is measured against cost; the gross margin is 60% because it is measured against selling price. Those percentages are not interchangeable, and neither one proves that the business is profitable.
All amounts below are teaching examples, not the prices or costs of the pictured Rustic Jewel Co set.
Define the sellable unit before doing the math
Cost and selling price must refer to the same unit. A pair of earrings can be one sellable unit even though it contains two physical pieces. A coordinated set can contain several pieces while still being ordered and priced as one set. Dividing the price by the number of visible components would answer a different question.
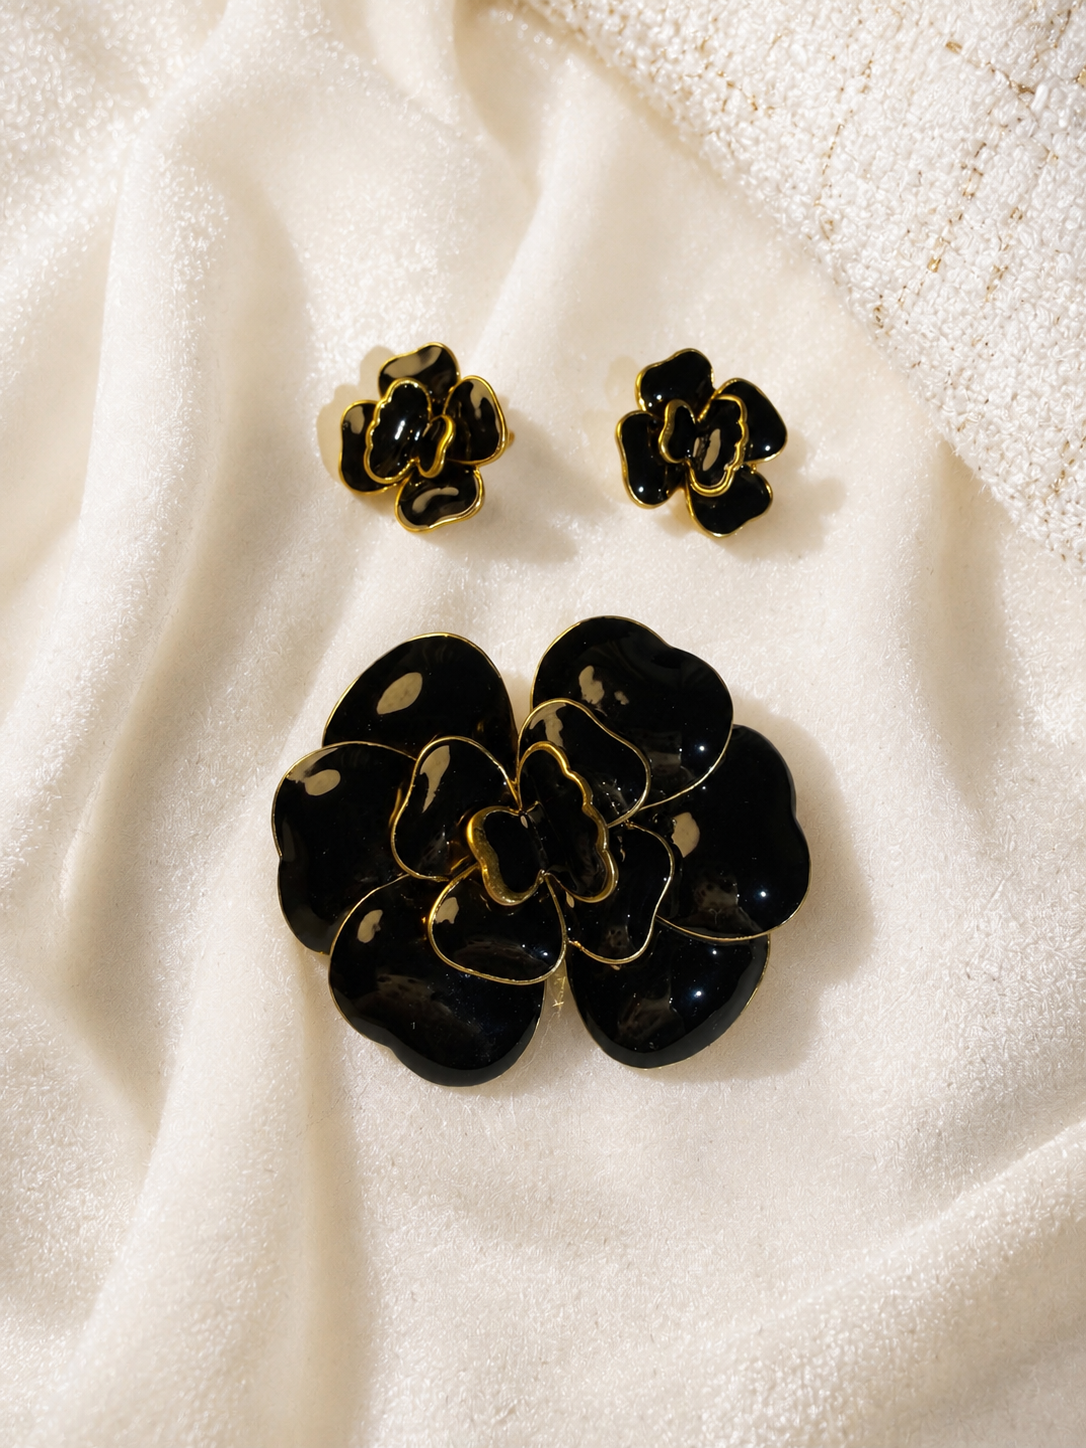
The Gold-Tone Black Enamel-Style Flower Brooch and Stud Earrings Set makes that distinction easy to see. The product includes one flower brooch and a matching pair of stud earrings—three physical pieces, but one advertised set.

When preparing buyer materials, the jewelry line-sheet guide explains how to label a price per pair, piece, or complete set without making the buyer decode the image.
Markup divides by cost; margin divides by revenue
Lightspeed's official pricing definitions distinguish markup as a percentage of cost and margin as a percentage of selling price. Using the same fictional $10-cost, $25-price set makes the denominator difference visible:
| Measure | Formula | Fictional result |
|---|---|---|
| Gross profit | Selling price − cost | $25 − $10 = $15 |
| Markup | Gross profit ÷ cost | $15 ÷ $10 = 150% |
| Gross margin | Gross profit ÷ selling price | $15 ÷ $25 = 60% |
The gross profit is the same $15 in both percentage calculations. Only the denominator changes. If a spreadsheet produces 150% and 60% from the same transaction, that is not a contradiction; the labels answer different questions.
Reverse the calculation before accepting a target
The difference becomes clearer when someone asks for “50%” without naming the measure. With the fictional $10 cost, a 50% markup produces a $15 selling price: $10 × (1 + 0.50). A 50% gross margin produces a $20 selling price: $10 ÷ (1 − 0.50).
That $5 gap comes entirely from the denominator. Before using a percentage in a quote, line sheet, or planning file, write either “markup on cost” or “gross margin on selling price.” The number alone is incomplete.
A markdown changes both the profit and the margin base
Now apply a 20% discount to the example's $25 selling price. The discount is $5, so the new selling price is $20. If the selected unit cost remains $10, gross profit becomes $10 and gross margin becomes 50%: ($20 − $10) ÷ $20.
Do not subtract 20 percentage points from the original 60% margin. A discount reduces revenue, which changes both the gross-profit numerator and the selling-price denominator. Recalculate from the new price each time.
Gross margin is not a promise of final profit
The calculation is only as clear as its cost basis. Record whether the unit cost already includes inbound freight, duty, packaging, or another direct amount. If a cost is already included, do not add it again. If it is excluded, keep that exclusion visible rather than letting readers assume the margin covers it.
Payment fees, outbound shipping, returns, labor, rent, marketing, and other operating costs may sit outside a simple product gross-margin calculation, depending on the business's accounting policy. This article does not decide their accounting or tax treatment. It only prevents a gross-margin percentage from being mistaken for operating or net profit.
Markup and margin also do not determine whether a wholesale order meets its quantity or value rules. The separate MOQ, MOV, and case-pack guide covers that eligibility calculation. For current Rustic Jewel Co commercial terms, use the wholesale and private client inquiry page rather than applying the fictional figures in this example.