
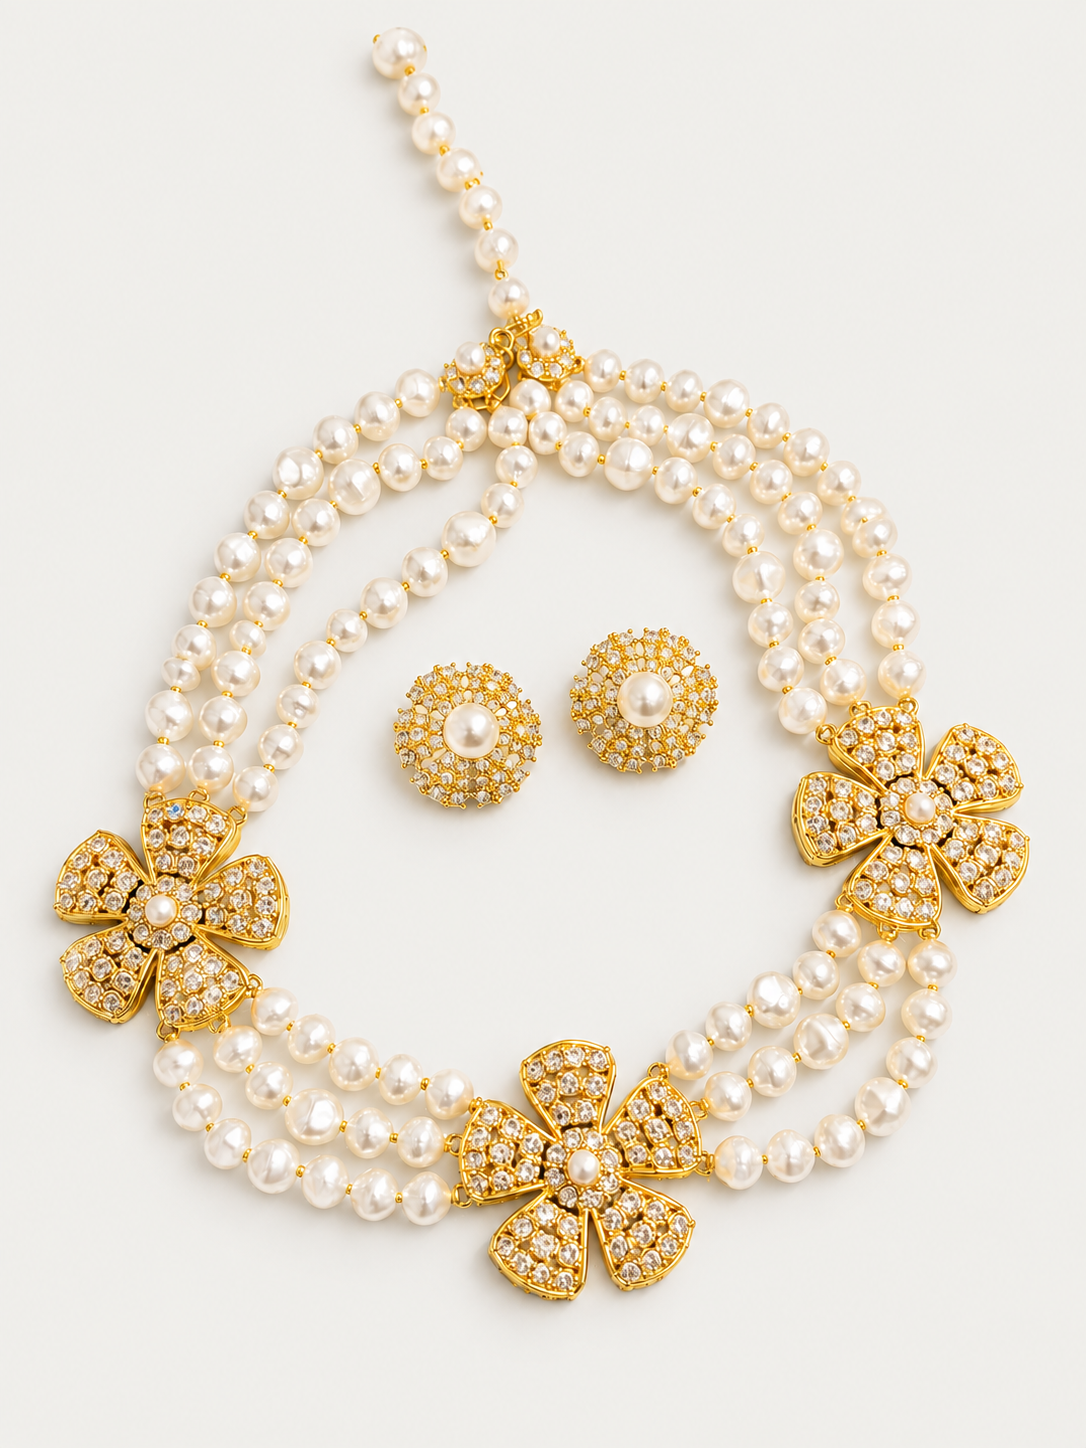
In a typical consignment arrangement, a boutique holds jewelry for sale while the supplier keeps ownership until a customer sale triggers settlement under the agreement. In a typical wholesale purchase, the boutique buys the stock and payment becomes due under the purchase or invoice terms. That wholesale payment might be required before shipment, at delivery, or later under agreed credit terms—it is not always paid before resale.
The difference is more than “pay now” versus “pay later.” Follow the stock's owner, the payment trigger, and the route for unsold goods. This is a general comparison, not advice on the legal or tax treatment of a particular agreement.
Separate ownership, custody, and payment
The IRS Retail Industry Audit Technique Guide, printed page 31, describes the general consignment model as goods held by the consignee while title remains with the consignor until sale. The guide also states that it is not a pronouncement of law, so it should not be treated as a substitute for an agreement or local professional advice.
| Operating question | Wholesale purchase | Consignment |
|---|---|---|
| Who owns stock while held? | Usually the buyer after ownership transfers under the purchase terms | Usually the supplier until a recorded sale or other agreed event |
| What makes payment due? | The invoice or purchase terms, not necessarily the boutique's resale | A customer sale followed by the agreed report and settlement timing |
| What happens to unsold stock? | It normally remains buyer-held stock unless return rights were agreed | It follows the agreed continue, recall, or return route |
| What must be reconciled? | Purchase order, receipt, invoice, payment, and buyer inventory | Delivery, custody, sales, unsold units, returns, and settlement |
Count complete selling sets, not visible pieces
The Pearl-Style Gold-Tone Flower Necklace & Earrings Set includes one necklace and a matching pair of earrings. Those three physical pieces make one advertised selling set. The photograph is useful for defining a complete unit; it is not a consignment offer, wholesale quote, or statement of Rustic Jewel Co terms.

Imagine four complete fictional sets are delivered to a boutique on consignment. One complete set sells and three complete sets remain in the store. The period reconciliation is four delivered, one sold, and three still held. The supplier and boutique would settle the one recorded sale according to their agreement while keeping the remaining three identified as consigned stock.
If the same four fictional sets had instead been purchased wholesale, the boutique's payment obligation would follow the invoice terms even if only one set had sold to a customer. The other three would remain part of the boutique's stock under the simplified example. In both models, the unit count is four sets—not twelve pieces—and a missing component would make a set incomplete rather than create a new sellable unit.
Write the payment trigger more precisely than “pay when sold”
For wholesale, record the invoice date, due date, currency, selling unit, and any agreed credit or deposit terms. The actual agreement—not the label “wholesale”—determines when payment is due.
For consignment, “pay when sold” still leaves operational questions. What counts as the sale date? How often does the boutique send a sales report? When is the related remittance due? Who can approve a discount, return, exchange, or customer refund? The answers should be confirmed before goods move rather than reconstructed from a month-end total.
Give unsold and changed stock a clear route
A consignment record should distinguish complete sets available for sale from sold, customer-returned, damaged, missing, recalled, or packed for return. Include where the goods are and when they were counted. The jewelry inventory worksheet offers a starting point for tracking those movements.
Unsold stock needs an agreed next step: continue for another period, return by a stated process, or follow another confirmed route. Damage, loss, shipping, insurance evidence, and discount authority also need answers from the actual parties. A general article cannot decide who bears those responsibilities.
For an outright wholesale purchase, use the jewelry purchase-order guide to confirm items, quantities, and prices. A purchase order alone will not track what sold on consignment or what the supplier is still owed.
Choose the model by the work it creates
Wholesale usually gives the boutique a defined inventory purchase and leaves it carrying the unsold-stock commitment unless different return terms apply. Consignment may reduce the immediate stock-purchase commitment, but it adds ongoing custody, sales reporting, unit reconciliation, settlement, and return work. Neither structure guarantees demand, margin, cash flow, or a simpler relationship.
For current Rustic Jewel Co buying terms, use the wholesale and private client inquiry page. This guide explains the two models; it does not offer a consignment arrangement.